HP Our Success Area
by The WSJ in 2023*
by RealTrends 2023*
Zillow and Yelp
Collective stats are sourced from the Condo Advisory submission
The Situation
We previously worked with a client to purchase primary and investment properties in San Francisco and the South Bay. The client had a liquidity event from a land sale and was looking to invest in real estate in the San Francisco condo market based on the data we provided. The data showed that the market had reached its trough and the statistics and early indicators we followed indicated a window of opportunity to purchase below historical trends and intrinsic long term value.
The Strategy
Our early indicators suggested the cyclical timing was right to consider a purchase for long term investment. From there, we analyzed data metrics to identify a list of potential target properties we were confident we could negotiate a deal with. We had time and an approach to create the conditions and relationships with listing agents to know when a seller was at the point of capitulation and ready to deal.
The Result
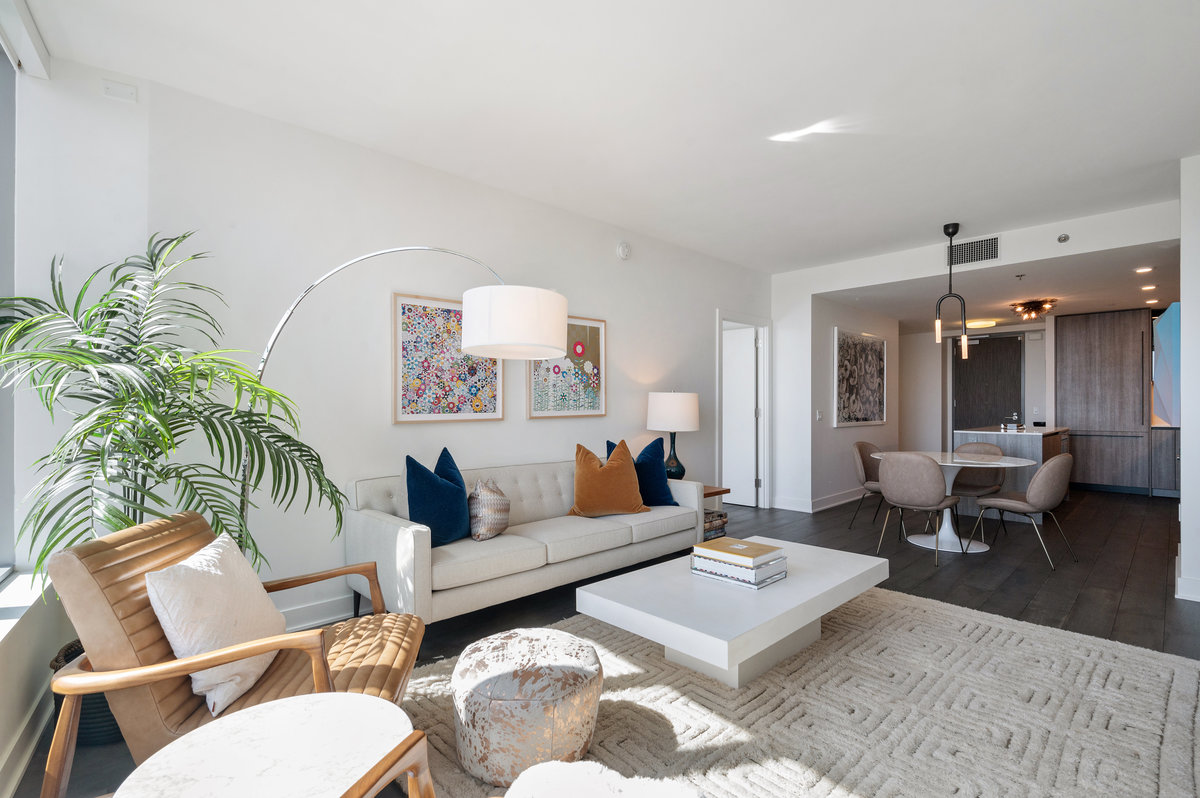
We closed on a luxury two bedroom, two bathroom + den with bridge and water views $400k under its original sale price, and appraised for $125k over the purchase price.
The Situation
We assisted a client in purchasing a condo in Hayes Valley and a new home in Rockridge. They needed a fast sale after closing on their new home to raise liquidity and reduce carry cost.
The Strategy
We arranged bridge financing to cover liquidity requirements while allowing us to utilize Compass Concierge to cover the cost of updates and staging and time the sale to capitalize on the Spring Market while adopting an off-market approach to a targeted list of buyers and agents.
The Result
We utilized financing options to eliminate out-of-pocket costs for the down payment on a new home while making their offer more appealing; thereby delaying the need to sell assets to avoid capital gains. Furthermore, we found a market buyer, eliminating the need to spend on improvements while selling at the originally planned list price, increasing the client's net proceeds at the close of escrow.
The Situation
We assisted a client purchase the top two condos in a four unit building in a superior Pacific Heights location. The prior owner had made the condos contiguous and used as a single family. However, it legally never converted to combine the two units and had alienated the HOA.
The Strategy
Buyer Approach: We did an extraordinary amount of due diligence and partnered with the HOA to amend the CC&R to keep eliminations of the combined condos while bringing the units within code compliance. However, we also preplanned how we would approach this if they resold and created a strategy/contingency plan if they opted for a resale.
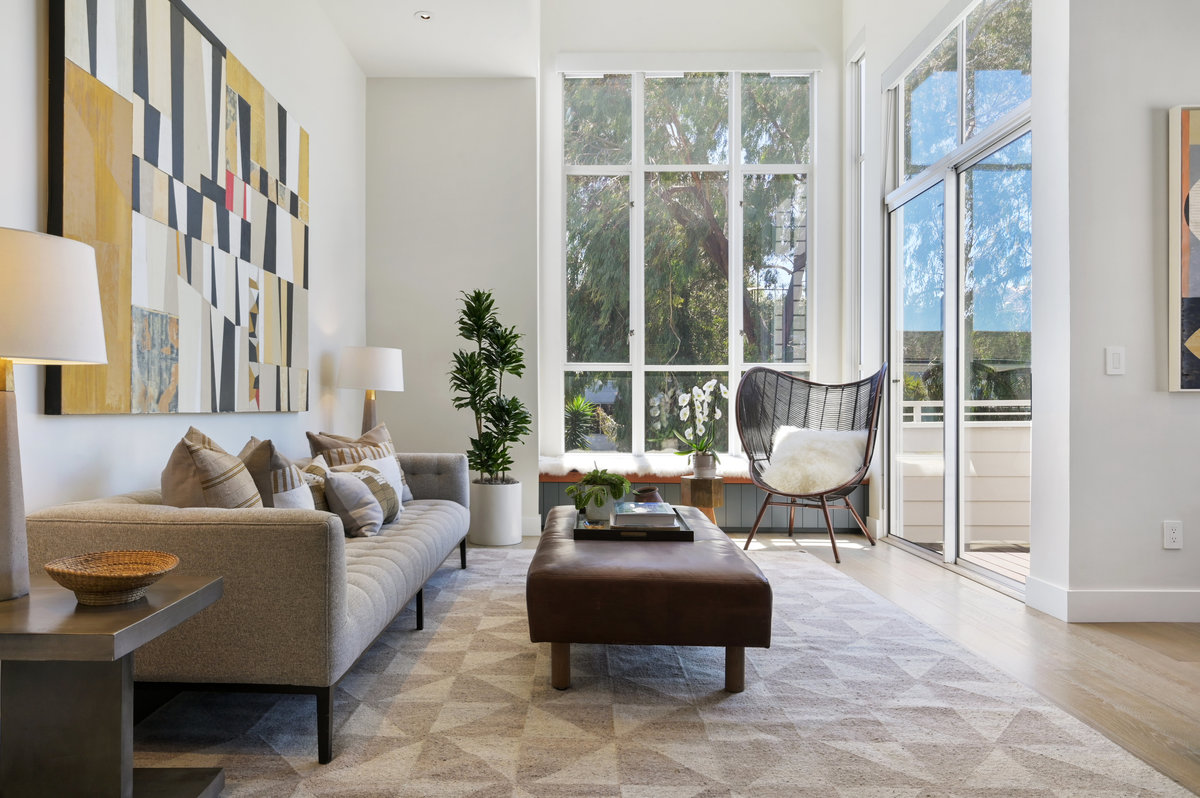
Seller Approach: We added elements, made cosmetic updates, and staged the home to feel and function like a large single-family or two separate condos. We marketed them as three listings to appeal to the broadest audience at a practically challenging year in recent markets.
The Result
Through our multi-channel approach and creating unique custom marketing for two units and a single-family use case through cosmetic updates and superior staging we received multiple offers and sold both units to one buyer over list price and superior to the individual offers for each condo unit.
In San Francisco’s fiercely competitive real estate landscape, every advantage can help win the day. Our robust network, crafted over two decades, coupled with cutting-edge AI technology, doesn’t just level the playing field—it elevates your position.
OFF-MARKET LISTINGSOur esteemed reputation, deep-rooted relationships within the Bay Area real estate community, and our affiliation with Compass—the market leader for homes at all price points in San Francisco—provide us with unparalleled access to the most extensive off-market inventory in the city. This exclusive information widens your home search and can help identify motivated sellers.
SIMPLIFIED TURNKEY SERVICESWe go beyond superficial engagement, offering seasoned insight based on multiple boom and bust real estate cycles. In addition to our network of top agents and cost-effective vendors, we offer streamlined client communications with market reports, timely activity reports, and curated recommendations. You will stay ahead of the curve while we work in the background.
ADAPTIVE VISION FOR TOMORROW’S OPPORTUNITIESWith a keen eye on emerging trends and opportunities and a combined 20 years of hands-on experience, Montgomery & Lee have successfully educated, motivated, and championed hundreds of buyers throughout the San Francisco Bay Area. With a hands-on approach, we guide our clients seamlessly through this opportunity with minimal stress.
We’d love to share our Buyer’s Guide that sheds light on our buying process and our strategies for optimizing it every step of the way.
The best time to buy a home in San Francisco depends on your financial readiness, housing needs, and what is happening in the local market. Rather than waiting for a perfect season or market shift, focus on whether the timing makes sense for your budget and long-term plans.
Rising interest rates may reduce purchasing power, but they can also result in less competition. Lower rates can improve affordability, but they often bring more buyers into the market and may place upward pressure on prices. Waiting for lower rates does not always mean paying less. Buyers can use the Consumer Financial Protection Bureau’s mortgage interest rate tool to compare how different rates could affect their costs.
Why neighborhood and property type matter: San Francisco is a collection of distinct real estate micro-markets. Luxury single-family homes in Noe Valley may perform differently from condominiums in Mission Bay or tenancy-in-common properties, commonly called TICs, in Duboce Triangle. Broad market headlines rarely tell the full story.
The best decision comes from evaluating personal goals alongside current neighborhood and property-specific conditions rather than trying to predict a perfect moment.
Before purchasing a San Francisco home, buyers should evaluate the property’s physical condition, permit history, ownership structure, ongoing costs, and long-term resale potential.
Review the disclosure package: Most sellers provide extensive disclosure packages before offers are due. These may include property inspections, seller disclosures, permit records, preliminary title reports, HOA documents, natural hazard reports, and other information. The California Department of Real Estate provides additional guidance in its Disclosures in Real Property Transactions publication.
Investigate older-building conditions: Older San Francisco homes may have soft-story construction, aging foundations, knob-and-tube wiring, galvanized plumbing, seismic retrofit considerations, or improvements completed without permits. Buyers can check available records through the city’s Property Information Map and review information about San Francisco’s Mandatory Soft Story Retrofit Program.
Evaluate condominium finances and governance: Condominium buyers should examine HOA financial statements, reserve funding, insurance coverage, litigation history, meeting minutes, planned projects, and upcoming special assessments.
Consider the surrounding area: Neighborhood trends, transportation, school information, zoning, planned construction, commute patterns, and long-term resale potential can be just as important as the home itself. San Francisco Planning’s Housing Dashboard provides information about completed housing and active residential projects in the development pipeline.
An informed buyer evaluates both the visible property and the risks, costs, and opportunities that may not be apparent during a showing.
The strongest offer is not always the offer with the highest price. It is often the offer that combines competitive terms with credible evidence that the transaction can close successfully.
Strengthen financial readiness: Sellers may consider the buyer’s financial qualifications, loan approval, deposit amount, available funds, and overall certainty of closing. A mortgage preapproval can help demonstrate that a lender has completed an initial review of the buyer’s finances.
Match the seller’s priorities: The proposed closing date, rent-back terms, contingency periods, possession timing, and flexibility may influence the seller’s decision.
Understand the risks: Buyers should not waive inspections, financing protections, appraisal contingencies, or other safeguards without understanding the possible financial and legal consequences.
Build a balanced offer: A successful negotiation aligns the buyer’s objectives with the seller’s priorities while protecting the buyer’s financial position and long-term interests.
Compass Private Exclusives allow sellers to market their homes privately before publicly listing them on the MLS.
Potential benefits for buyers: Buyers working within the Compass network may learn about properties that have not yet entered the broader public market. This can provide earlier access, although availability and competition will vary by property.
Before making an offer, buyers should review the property’s inspection reports, seller disclosures, permit history, preliminary title report, natural hazard disclosures, insurance information, and records of known repairs or defects.
Condominium buyers should also examine the HOA’s financial statements, reserve funding, insurance coverage, meeting minutes, governing documents, planned projects, litigation, and potential special assessments.
Buyers should research zoning, comparable sales, neighborhood conditions, transportation, and proposed development. The San Francisco Property Information Map and Development Pipeline Map can provide useful property and planning information.
A thorough review helps buyers understand the home’s condition, ongoing costs, and potential risks before committing to the purchase.
One of the biggest mistakes buyers make is allowing emotion, market headlines, or incomplete information to guide a major financial decision.
Buyers may focus too heavily on the purchase price while overlooking inspection findings, financing costs, insurance, HOA expenses, contingencies, and long-term resale potential.
Both buyers and sellers benefit from making decisions based on reliable data, property-specific research, and current neighborhood conditions.
Whether to buy your next home before selling your current one depends on your financing, available equity, risk tolerance, and how quickly you expect your existing property to sell.
Buying first can give you more control over your home search and moving timeline, but it may require bridge financing or the ability to qualify while still carrying your current property. Selling first can clarify how much you have available for your purchase, but it may create pressure to find a new home quickly or arrange temporary housing.
Before deciding, compare both scenarios based on financing, expected sale proceeds, carrying costs, and what happens if either transaction takes longer than planned.
Montgomery + Lee helps buyers coordinate the purchase of a new home with the sale of an existing one, so financing, timing, and both transactions are considered together.
A condominium buyer owns an individual unit and a shared interest in the building’s common areas. A tenancy-in-common, or TIC, buyer owns a percentage of the entire property with other co-owners.
In a TIC, the right to occupy a particular unit is usually established through a written agreement. Buyers should review how that agreement addresses financing, insurance, repairs, shared expenses, voting, disputes, and future sales.
TIC financing and resale procedures can differ from those of a condominium, so buyers should review the ownership structure carefully. The California Department of Real Estate’s Tenancy in Common Guidelines provide additional information about TIC agreements and ownership arrangements.
Buying a tenant-occupied property generally means acquiring it subject to the existing tenancies, leases, and applicable tenant protections. The sale itself does not require tenants to move.
Buyers should review all leases, rent records, security deposits, notices, tenant correspondence, and Rent Board filings. They should also confirm when each tenancy began, what rent is being collected, and whether any buyout agreements or disputes exist.
San Francisco has specific tenant disclosure requirements before and after the sale of a rental property. Plans involving owner occupancy, renovation, or future vacancy should be reviewed with a qualified landlord-tenant attorney before making an offer.
Unpermitted work creates uncertainty about whether an alteration was reviewed, inspected, completed to code, or legally recognized as part of the property.
Buyers should compare the current layout with available permits, approved plans, inspection records, and the property’s legal use. Converted garages, lower-level rooms, added bathrooms, roof decks, and structural changes often require closer review.
Buyers can request building permits, plans, and other public building records from the San Francisco Department of Building Inspection. The level of risk depends on what was built, whether it can be legalized, and how lenders, insurers, appraisers, or future buyers may view it.
Buyers should evaluate the building’s foundation, construction, site conditions, retrofit history, and current structural condition rather than relying on age alone.
Potential concerns may include large garage openings, visible settlement, drainage issues, retaining walls, hillside conditions, or past structural alterations. Buyers can also review San Francisco’s earthquake safety rules and seismic retrofit programs. A completed retrofit can reduce certain risks, but it does not make a building earthquake-proof.
A general inspection may identify warning signs, while more significant concerns should be evaluated by a licensed structural engineer.
Buyers should budget for property taxes, insurance, closing expenses, maintenance, utilities, and building-specific costs in addition to the mortgage payment.
A purchase may result in supplemental property-tax assessments after the home is reassessed at its new value. These bills are issued separately from the regular annual property-tax bill.
Condominium and TIC buyers should also account for monthly dues, shared insurance, capital projects, and possible special assessments. Older homes may require larger reserves for roofing, foundations, exterior work, plumbing, or electrical systems.
A low appraisal can reduce the amount a lender is willing to finance, creating a gap between the purchase price and the appraised value.
The buyer may contribute additional cash, request a price reduction, challenge the appraisal with relevant information, negotiate another solution, or reconsider the purchase. The Consumer Financial Protection Bureau explains what a low appraisal can mean for a homebuyer.
Buyers should evaluate appraisal risk before making an offer, especially when a home is expected to sell above recent comparable sales. Any decision to limit or waive an appraisal contingency should be made with a clear understanding of the potential cash requirement.
The right neighborhood is the one that supports the buyer’s daily routine, housing preferences, and long-term plans.
Buyers should compare commute routes, public transportation, parking, walkability, weather, topography, outdoor access, street noise, and proximity to the places they expect to visit regularly. They should also consider whether they prefer a single-family home, condominium, TIC, or loft, since housing options vary significantly by neighborhood.
Visiting an area at different times of day can reveal changes in traffic, sunlight, wind, noise, and overall atmosphere. Buyers can also use the San Francisco Planning Department’s Property Information Map to research zoning, permit history, property details, and other government-held information.
AI can help buyers organize listings, compare properties, summarize documents, and develop useful questions during a home search. It should not be treated as the final authority on a property’s value, condition, ownership, or legal status.
Automated tools may miss factors that can significantly affect San Francisco real estate, including natural light, views, floor-plan quality, tenant occupancy, permit history, architecture, parking, and block-specific demand.
Any AI-generated summary should be checked against the original inspections, disclosures, permits, title records, or HOA documents. Technology is most useful when it helps buyers evaluate verified information alongside experienced, property-specific guidance.
Montgomery + Lee provides San Francisco buyers and sellers with local expertise, property-specific analysis, strategic negotiation, and detailed transaction guidance.
The team has advised clients across a range of San Francisco neighborhoods, property types, price points, and market conditions. Its approach combines market data, strategic pricing, due diligence, and careful transaction management.
Montgomery + Lee works as a trusted advisor, helping clients understand their options, manage potential risks, and make decisions that support their immediate goals and long-term interests.